Overview of the Uranium Ore Market
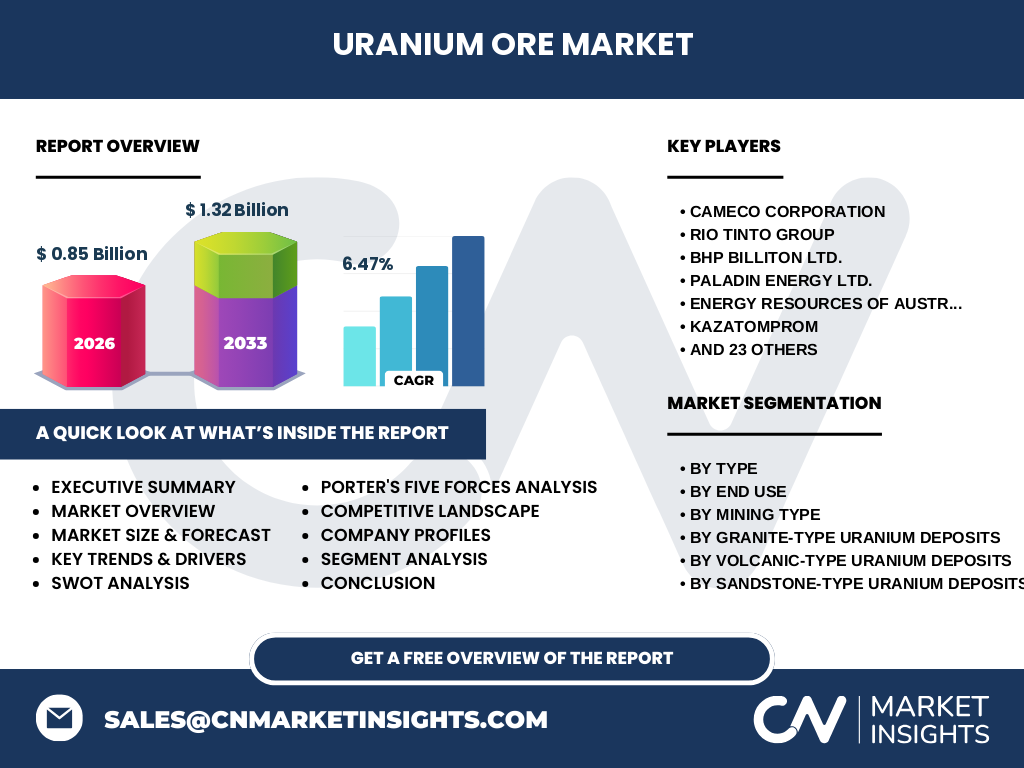
The Uranium Ore Market serves as the bedrock for the global nuclear fuel cycle. Valued at 0.85 Billion in 2026, the sector encompasses the extraction of radioactive mineral deposits essential for nuclear power generation. Our analysis identifies this as a critical strategic commodity, where geological expertise dictates the viability of mining operations ranging from sandstone-hosted to volcanic-type deposits.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by the decarbonization mandate, pushing nuclear as a baseload energy provider. We project a 6.47% CAGR through 2033, though constraints remain. Logistical hurdles, including strict International Atomic Energy Agency (IAEA) regulations and the complex extraction of sandstone-hosted roll-front deposits, force companies like Cameco and Kazatomprom to navigate localized geopolitical risks and significant environmental compliance costs.
Emerging Trends and Strategic Patterns
The market is shifting toward in-situ recovery (ISR), particularly in sandstone-hosted deposits, to minimize ecological footprints. We observe an increasing institutional interest in uranium as a financial asset, evidenced by the strategic holdings of Yellow Cake plc and Uranium Royalty Corp. This trend decouples supply availability from immediate reactor consumption, tightening physical inventories.
Impact of COVID-19 and Subsequent Recovery
The pandemic acted as a catalyst for supply chain consolidation. Disrupted logistics at key mining sites in Canada and Kazakhstan forced an accelerated shift toward automated mining technologies. Post-2021, the recovery trajectory has been robust, as global governments prioritized energy sovereignty, leading to the current market valuation of 0.85 Billion and setting the stage for steady growth.
Competitive Benchmarking and Market Dynamics
The landscape is dominated by heavyweights like Kazatomprom, Cameco, and Orano, who leverage vast state-backed reserves. Meanwhile, juniors like NexGen Energy and Fission Uranium focus on high-grade unconformity-related discoveries. Our analysis indicates a bifurcated market where Tier-1 producers focus on volume, while exploration-stage companies drive the innovation pipeline required to replenish dwindling global reserves.
Executive Summary: Uranium Ore Market Outlook
Our research forecasts the Uranium Ore Market to reach 1.32 Billion by 2033. This growth is underpinned by nuclear life-extensions and the deployment of Small Modular Reactors (SMRs). Investors should monitor the shift from traditional mining to ISR, as this dictates the future of operational cost efficiency across the global energy infrastructure.
Market Forecast: 2027 to 2033
We anticipate a steady climb to 1.32 Billion by 2033. The 6.47% CAGR reflects a transition from surplus to structural deficit. As major mines reach maturity, the development of new projects by companies such as Denison Mines and Uranium Energy Corp will be essential to meeting the projected energy demand spikes in emerging economies.
Segmentation Analysis: Categorizing the Ore Landscape
The market splits into diverse geological types, with Sandstone-Type Deposits—particularly roll-front systems—representing a vital mining focus. End-use segmentation spans Nuclear Power Generation, medical, and defense. Each segment relies on unique geometallurgical processing techniques, where mining type—whether Underground or Surface—determines the localized operational expenditure and environmental impact profile.
Regional Market Performance and Distribution
Regional dominance remains concentrated in Kazakhstan, Canada, and Australia. Our data shows that while Kazatomprom leads in low-cost ISR production, Canadian producers focus on high-grade, deep underground mining. These localized strategies create a complex map of trade flows, influenced by Nuclear Regulatory Commission (NRC) standards and shipping access through ports like Darwin or Vancouver.
In-depth Regional Review: Strategic Hotspots
Central Asia continues to act as the primary global supply hub, with Navoi Mining playing a pivotal role. Simultaneously, North America has seen a resurgence in exploration investment, driven by energy independence initiatives. The interplay between Western regulatory frameworks and Eastern production capacity remains a defining feature of the international Uranium Ore Market.
Company Profiles and Strategic Positioning
Leading players like Rio Tinto and BHP manage diversified portfolios where uranium is a strategic by-product. Conversely, pure-play entities like Paladin Energy and Deep Yellow are laser-focused on asset reactivation. This competitive matrix reveals that companies with strong balance sheets and advanced permitting status are currently positioned to capture the greatest share of future growth.
Porter's Five Forces: Competitive Assessment
The Uranium Ore Market faces high barriers to entry due to intense regulatory scrutiny and capital-intensive exploration. While supplier power is high due to resource concentration, the bargaining power of buyers is moderated by long-term fuel procurement contracts. Competition is fierce among current producers to secure new licensing agreements for high-grade, untapped volcanic or granite-type deposits.
SWOT Analysis: Strategic Evaluation
Strengths: Established supply chains and rising demand. Weaknesses: High environmental compliance risks. Opportunities: Small Modular Reactor integration and long-term price appreciation. Threats: Potential for geopolitical instability in key mining regions and the high cost of Underground Mining safety protocols. These factors define the tactical landscape for all major market participants.
Value Chain Analysis: From Ore to Energy
The chain flows from geological prospecting and mining to milling, refining, and conversion. Players like CGN Mining integrate vertically to ensure security of supply. The critical nodes are the conversion and enrichment facilities, where raw Uranium Ore is transformed into nuclear-grade fuel assemblies, ultimately servicing the global reactor fleet.
Investment Insights and Strategic Recommendations
We recommend focusing on companies with permitted projects near production, particularly those utilizing ISR technology in sandstone deposits. With the market set to reach 1.32 Billion, equity positions in entities like NexGen or Boss Resources offer exposure to high-grade resources that remain unexploited, providing a hedge against the inevitable long-term structural supply deficit.
Conclusion and Key Takeaways
The Uranium Ore Market is undergoing a fundamental revaluation. Driven by a 6.47% CAGR and the strategic imperative of carbon-free baseload power, the industry is transitioning toward more efficient extraction and sustained investment. Success in the next decade will belong to those who can bridge the gap between environmental stewardship and the increasing demand for energy security.
Research Methodology: Triangulation of Data
Our estimates are triangulated via primary stakeholder interviews with mining executives, analysis of Trade Registry data from major producing nations, and macroeconomic modeling of global reactor deployment. We cross-verify these with secondary indicators including quarterly financial reports and public disclosure documents to ensure the 0.85 Billion baseline is accurate and actionable for our clients.
Scope of the Report and Limitations
This analysis covers the global Uranium Ore Market from 2026 to 2033, including all major mining types and geological deposits. Limitations include potential regulatory shifts and geopolitical trade restrictions which may alter production timelines. Our focus remains on the commercial and strategic viability of the industry, specifically excluding non-commercial experimental research activities.
Recent Developments in the Industry
Recent activity is defined by strategic partnerships and M&A consolidation. Companies like Uranium Energy Corp have actively acquired assets to expand their U.S.-based production capabilities. Simultaneously, global partnerships between CNNC and international miners reflect an ongoing race to secure long-term supply contracts as the market prepares for the anticipated 1.32 Billion growth phase.